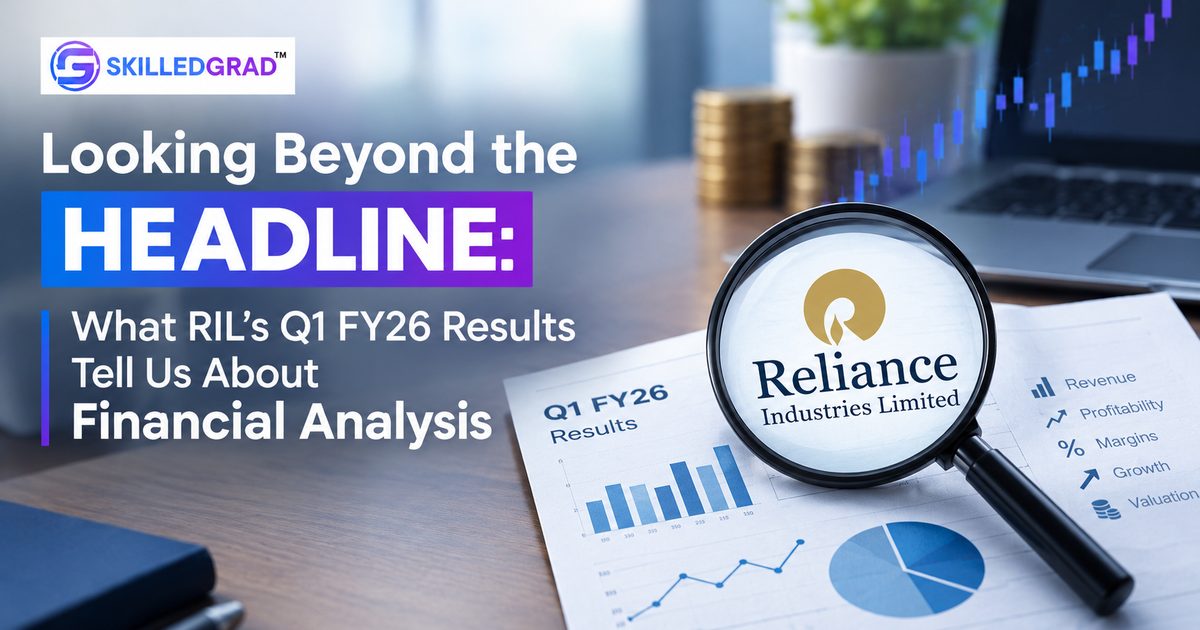
Reliance Industries reported around 78% year-on-year growth in profit attributable to shareholders in Q1 FY26, but the quarter also included a ₹8,924 crore gain from selling its Asian Paints investment. The gain was valid reported income, yet it was not a recurring operating result. For analysts, the lesson is to separate reported profit from underlying business performance before drawing conclusions about sustainable growth.
A headline that deserves a closer look
Reliance Industries Limited’s Q1 FY26 results attracted attention with a 78% year-on-year increase in quarterly profit. At first glance, the number suggests a significant improvement in the company’s performance. However, a closer look shows why financial analysis cannot stop with headline numbers.
Contents
- A headline that deserves a closer look
- RIL Q1 FY26 results: headline growth versus recurring performance
- Why reported profit and underlying profit differ
- The accounting lesson: investment gains, FVOCI and OCI
- The role of framing bias in financial news
- Three questions every finance student should ask
- Frequently asked questions
- The bigger lesson
- Sources and reading
A major contributor was a gain of approximately ₹8,924 crore from the sale of Reliance’s investment in Asian Paints. This is an important distinction: a gain from selling an investment is fundamentally different from earnings generated by regular business operations.
This does not make the reported profit any less valid. The gain is real and appropriately included in the reported figures. The analyst’s question is different: how much of the improvement is recurring, and how much came from a one-time event?
Consider a simple example. If an individual earns ₹50,000 a month and also makes ₹2 lakh by selling an investment, income in that particular month is much higher. But it would be incorrect to conclude that monthly salary has risen by the same amount. The same principle helps us interpret corporate earnings.
RIL Q1 FY26 results: headline growth versus recurring performance
| Metric / observation | Q1 FY26 result |
|---|---|
| Profit attributable to owners, year-on-year growth | Approximately 78% |
| Gain on sale of Asian Paints investment | ₹8,924 crore |
| Recurring profit growth, as presented by RIL | Approximately 25% year on year |
The 78% and 25% figures refer to different profit presentations; they should not be treated as interchangeable. Reliance’s own analyst presentation reported approximately 25% growth in recurring profit alongside the one-time investment gain.
Why reported profit and underlying profit differ
Financial statements provide reported numbers, but analysis requires us to understand the reasons behind them. Profits may rise because revenue grows, margins improve or costs fall. They can also be influenced by asset disposals, investment gains, exceptional items and other events that may not repeat.
That is why analysts often adjust reported earnings when assessing underlying performance. The objective is not to ignore accounting profit, but to understand the quality and sustainability of that profit.
The accounting lesson: investment gains, FVOCI and OCI
The transaction also creates an opportunity to discuss how investments are accounted for. Under Ind AS, the classification of a financial asset influences whether changes in fair value appear in profit or loss or in Other Comprehensive Income (OCI). For certain equity investments designated at Fair Value Through Other Comprehensive Income (FVOCI), cumulative gains are generally not recycled to profit or loss upon disposal.
It is therefore essential to check the company’s disclosures before assuming how a particular gain has entered reported profit. The ₹8,924 crore Asian Paints sale gain was reported by Reliance in its Q1 FY26 results; the general FVOCI rule should not be presented as the mechanism that automatically produced that profit-and-loss gain. The broader lesson remains: understand the accounting treatment, not merely the headline.
The role of framing bias in financial news
“RIL profit rises 78%” creates one immediate impression.
“RIL profit rises 78%, including a ₹8,924 crore gain from selling an investment” provides considerably more context.
The underlying information has not changed, but the wording influences our first interpretation. This is a practical example of framing bias: our judgement can be affected by how facts are presented.
Three questions every finance student should ask
What changed?
Why did it change?
Is the change likely to continue?
These simple questions are the foundation of meaningful financial analysis. The RIL results bring together reported earnings, non-recurring gains, analyst adjustments, financial reporting and behavioural biases, concepts that students often encounter separately.
Frequently asked questions
What caused RIL’s profit to rise sharply in Q1 FY26?
Reported profit benefited from operating performance as well as a ₹8,924 crore gain on the Asian Paints investment sale. The sale gain was a significant non-recurring contributor.
What is a non-recurring gain?
It is a gain arising from an event, such as a particular investment sale, that is not ordinarily expected to recur every reporting period.
Why do analysts calculate adjusted or recurring earnings?
To assess how much of reported profit reflects the ongoing economics of the business, while making the adjustments and their rationale transparent.
The bigger lesson
The real value of studying this result is not simply knowing that Reliance’s profit increased by 78%. It is understanding what was behind that 78%. That is where financial statements move from numbers on a page to tools for understanding a business.
At Skilledgrad, we believe finance is best understood when classroom concepts connect to what is happening in companies and markets. The objective is not just to know finance. It is to see finance happening around you.
Sources and reading
Reliance Industries, Q1 FY26 Financial Presentation (18 July 2025)
Reliance Industries, Q1 FY26 financial reporting
Business Standard, 18 July 2025, report on RIL Q1 FY26 and Asian Paints stake sale
Prepare with Skilledgrad
Classroom coaching at Purasaiwakkam and Tambaram, with structured classes, question practice, tests and one-on-one mentoring. Talk to us about the batch and exam window that suit you.