Net Present Value (NPV) compares the present value of a project’s expected future cash inflows with its initial investment. A positive NPV indicates expected value creation at the required return; a negative NPV indicates that the project falls short. This is a core investment appraisal concept for ACCA Financial Management and is also relevant to CFA studies.
Imagine you are planning to start a small business. You need to invest ₹1,00,000 today, and you expect the business to generate cash over the next three years.
Contents
The total cash you expect to receive is ₹1,20,000.
At first glance, the investment looks attractive. You invest ₹1,00,000 and receive ₹1,20,000. That is ₹20,000 more than your initial investment.
But there is something we need to consider.
You are not receiving the entire ₹1,20,000 today. The money will arrive over the next three years. And as we explored in Part 1, money received in the future is worth less than the same amount received today.
So, how do we decide whether this investment is actually worthwhile?
This is where Net Present Value (NPV) comes in.
From Present Value to NPV
In our previous blog, we learned how to convert future cash flows into their present value using discount factors.
NPV takes this idea one step further.
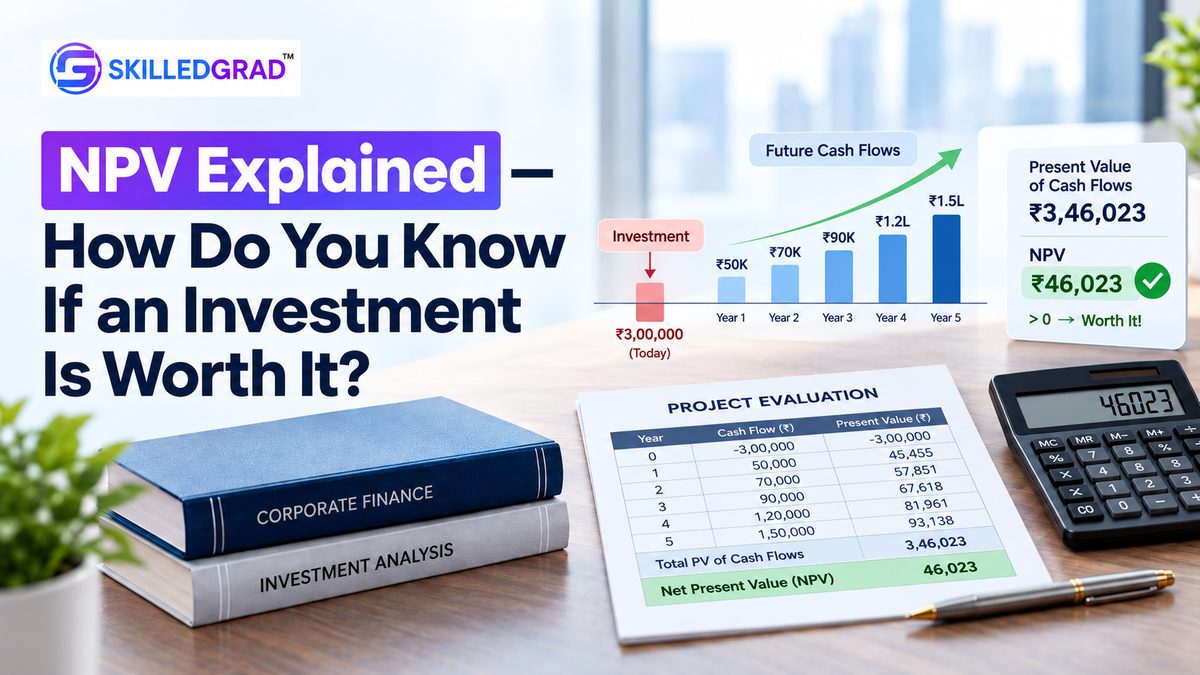
It calculates the present value of all the future cash flows generated by an investment and then subtracts the amount invested today.
NPV = Present Value of Future Cash Flows − Initial Investment
The logic is straightforward. First, determine what the future cash inflows are worth today. Then compare that amount with what you need to invest.
Let's work through an example.
Let's calculate NPV
Suppose you are considering a project that requires an initial investment of ₹1,00,000. The project is expected to generate ₹40,000 at the end of each of the next three years.
Assume that your required rate of return is 10% per year.
The expected cash flows are:
| Year | Cash flow |
|---|---|
| Today (Year 0) | −₹1,00,000 |
| Year 1 | ₹40,000 |
| Year 2 | ₹40,000 |
| Year 3 | ₹40,000 |
The project will generate ₹1,20,000 in total. But we cannot simply compare ₹1,20,000 with ₹1,00,000 because the cash inflows arrive at different points in time.
We must first calculate their present values.
Using the 10% discount rate, we obtain the following discount factors:
| Year | Cash inflow | Discount factor | Present value |
|---|---|---|---|
| 1 | ₹40,000 | 0.9091 | ₹36,364 |
| 2 | ₹40,000 | 0.8264 | ₹33,058 |
| 3 | ₹40,000 | 0.7513 | ₹30,053 |
| Total | ₹1,20,000 | ₹99,475 |
The total present value of the future cash inflows is approximately ₹99,475.
Now we can calculate NPV.
NPV = ₹99,475 − ₹1,00,000
NPV ≈ −₹525
The project has a negative NPV of approximately ₹525.
Although the project generates ₹1,20,000 over three years, the present value of those receipts is slightly less than the initial investment of ₹1,00,000.
At a required return of 10%, the project falls just short of the return we want.
What does a positive or negative NPV actually mean?
Let's look at three possible outcomes.
Positive NPV
Suppose a project has an NPV of ₹25,000.
This means the present value of its future cash inflows exceeds the initial investment by ₹25,000. After allowing for the required return, the project is expected to create additional value of ₹25,000 today.
All else being equal, this is an attractive investment.
Negative NPV
Suppose a project has an NPV of −₹15,000.
The present value of the future cash inflows is ₹15,000 less than the initial investment. The project is not expected to earn the required return.
Based on the financial estimates, it would generally be rejected.
Zero NPV
Suppose a project has an NPV of zero.
The present value of its future cash inflows exactly equals the initial investment. The project is expected to earn the required rate of return, neither creating nor destroying additional value relative to that benchmark.
For a conventional investment, the basic decision rule is therefore:
| NPV result | Decision |
|---|---|
| Positive | Accept, subject to other relevant considerations |
| Negative | Reject, subject to other relevant considerations |
| Zero | Financially meets the required return |
Why does the required rate of return matter?
Let's return to our original project.
We calculated an NPV of approximately −₹525 using a required return of 10%.
But what if you only required a return of 8%?
The present value of the future cash inflows would be higher because we would be discounting them at a lower rate. The NPV would become positive.
What if you required a return of 12% instead?
The present value of the future cash inflows would fall, making the NPV more negative.
The cash flows have not changed. What has changed is the return you require from the investment.
This is an important point: NPV depends not only on the expected cash flows but also on the required rate of return.
In practice, the required return should reflect the opportunity cost of investing the money elsewhere and the risk of the project.
Where is NPV used in real business decisions?
Imagine a company considering the purchase of a new machine.
The machine costs ₹50 lakh today and is expected to generate additional cash flows over the next five years. The company must decide whether those future benefits justify the initial expenditure.
Simply adding up the expected cash inflows is not enough. The company needs to account for when the cash will arrive and the return required for taking on the investment.
NPV helps the company estimate whether the investment is expected to create value.
The same principle applies when a business considers opening a new branch, expanding production capacity, launching a new product or investing in a long-term project.
This is why NPV is an important concept in Financial Management and professional finance and accounting qualifications such as ACCA and CFA.
One thing to remember
NPV and total profit are not the same thing.
In our example, the project generates ₹20,000 more in total cash inflows than the initial investment. Yet its NPV is negative at a required return of 10%.
Why? Because the cash inflows arrive over three years, and their present value is lower than their total nominal amount.
NPV considers both the timing of cash flows and the required return. That makes it more useful than simply comparing the amount invested with the total cash expected to be received.
What comes next?
NPV tells us how much value an investment is expected to create in today's terms.
But there is another question we may want to ask:
What annual rate of return does this investment offer?
Instead of choosing a discount rate and calculating NPV, can we work backwards and find the rate at which the NPV becomes zero?
That is exactly what the Internal Rate of Return (IRR) helps us determine.
We will explore IRR in Part 3: IRR explained.
The takeaway
NPV brings together the concepts of present value, discount factors and investment appraisal.
It helps us move beyond the question, “Will I get back more money than I invest?” and ask a more meaningful question:
“After accounting for the time value of money and my required return, will this investment create value?”
That is the real purpose of NPV.
Prepare with Skilledgrad
Classroom coaching at Purasaiwakkam and Tambaram, with structured classes, question practice, tests and one-on-one mentoring. Talk to us about the batch and exam window that suit you.